 by
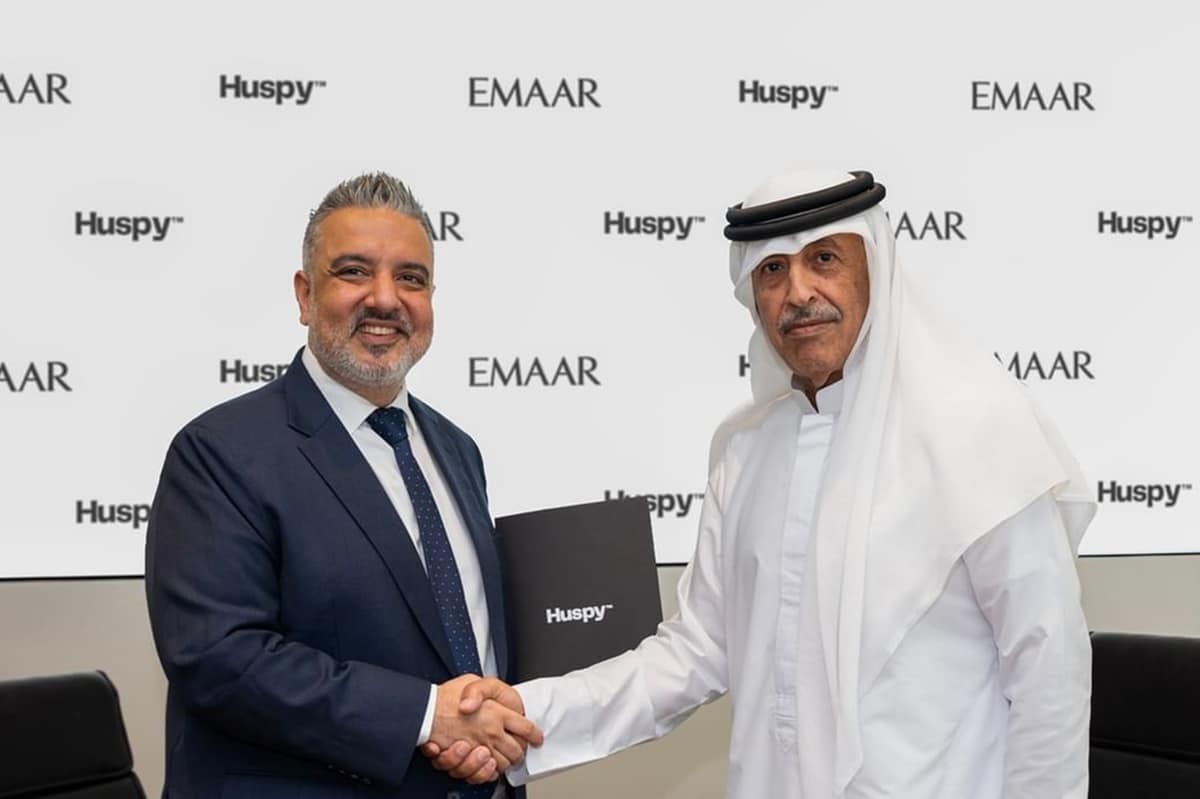
Dubai’s property market continues to attract international buyers, particularly Indian investors looking for long term wealth creation, rental income and a place to call home. However, choosing the right mortgage remains an important part of purchasing property in the UAE. A new collaboration between Emaar Properties and UAE based mortgage technology company Huspy aims to simplify this process. Through this initiative, Emaar customers can access mortgage advisory services and financing options from more than 20 banks across the UAE. The service allows buyers to compare mortgage products, interest rates and financing terms through one platform. For Indian homebuyers planning to purchase property in Dubai, this development brings greater convenience, more financing choices and professional assistance throughout the mortgage journey.
Dubai Mortgage Comparison: What Does the Emaar and Huspy Partnership Offer?
Emaar Properties has partnered with Huspy to make property financing more accessible to its customers. The collaboration provides access to mortgage products and financing options from more than 20 UAE banks.
Instead of approaching multiple banks individually, eligible Emaar customers can explore different mortgage options through Huspy’s platform.
The service includes:
- Mortgage product comparisons from more than 20 UAE banks.
- Access to different interest rates and financing terms.
- Personalised mortgage guidance.
- Assistance with mortgage pre approval.
- Support with documentation and bank coordination.
- Guidance until mortgage disbursal.
- No Huspy advisory fees for the service.
The initiative covers different stages of property ownership, including property purchases, property handovers and refinancing.
For buyers, this can make the financing process more organised and easier to understand.
Mortgage Rates in Dubai: Why Comparing Multiple Banks Matters
Choosing a mortgage is not simply about finding the lowest advertised interest rate. Buyers should understand the complete financing structure before making a commitment.
Different banks may offer different rates, repayment periods, eligibility conditions and processing fees.
A proper UAE Mortgage Comparison helps buyers evaluate these factors before selecting a lender.
Here are some important factors to consider:
1. Interest Rates and Repayment Terms
Mortgage rates directly influence monthly repayments and the overall borrowing cost.
Some banks offer fixed interest rates for an initial period, while others provide variable rate structures linked to a benchmark.
Buyers should compare the initial rate, the rate after the fixed period and the total repayment obligation.
2. Processing Fees and Additional Charges
Apart from interest rates, homebuyers should check additional costs associated with financing.
These may include:
- Bank processing fees.
- Property valuation charges.
- Mortgage registration fees.
- Property insurance.
- Life insurance.
- Early settlement charges, where applicable.
Understanding these expenses helps buyers calculate the actual cost of purchasing a property.
3. Loan Eligibility and Down Payment
Banks assess several factors before approving a mortgage.
These generally include income, employment status, existing financial commitments, credit history and property value.
The required down payment also depends on the buyer’s residency status, property value and applicable lending regulations.
Home Loans in UAE: What Indian Buyers Should Know
Indian nationals represent an important international buyer segment in Dubai’s residential property market.
Many Indian professionals, entrepreneurs and business owners consider Dubai because of its international lifestyle, connectivity, business environment and property investment opportunities.
However, before applying for Home Loans in UAE, Indian buyers should understand the basic requirements.
Can Indian Expats Apply for a Dubai Mortgage?
Yes. Eligible Indian expatriates who are UAE residents can apply for home financing through participating banks.
Non resident Indian buyers may also find mortgage options through selected UAE lenders, subject to individual bank policies and eligibility requirements.
Approval is not automatic. Each bank evaluates the applicant’s financial profile.
Important Documents for Indian Homebuyers
Although requirements differ between banks, buyers may be asked to provide:
- Passport copy.
- UAE residence visa and Emirates ID, where applicable.
- Salary certificate or employment confirmation.
- Recent bank statements.
- Salary slips, where required.
- Details of existing loans and financial commitments.
- Property booking documents or sale agreement.
- Additional financial documents requested by the lender.
Self employed Indian buyers may need to provide company documents, trade licences, financial statements and business bank statements.
Preparing documents in advance can help reduce delays during the application process.
Dubai Property Financing: How the Mortgage Process Works
Understanding the mortgage process helps buyers plan their property purchase more confidently.
With the Emaar and Huspy collaboration, customers can receive guidance through several important stages.
Step 1: Understand Your Financial Eligibility
Before selecting a property, calculate your affordability.
Consider your monthly income, existing financial commitments, available savings and expected monthly mortgage repayments.
This helps establish a realistic purchasing budget.
Step 2: Compare Available Mortgage Options
Explore financing products from different UAE banks.
Compare interest rates, fixed periods, loan terms, processing fees and eligibility requirements.
A wider comparison can help buyers identify financing options that suit their financial circumstances.
Step 3: Obtain Mortgage Pre Approval
Mortgage pre approval provides an initial indication of the amount a bank may be willing to finance.
It helps buyers understand their purchasing capacity before proceeding with a property transaction.
However, final approval remains subject to the bank’s checks, property valuation and documentation.
Step 4: Complete Property and Bank Documentation
After selecting a property, the buyer proceeds with the required documentation.
The bank reviews the property details, completes its valuation and carries out the necessary checks before issuing its final offer.
Step 5: Mortgage Approval and Disbursal
Once the required conditions are satisfied, the bank completes the mortgage approval process and arranges the disbursal according to the agreed transaction terms.
Professional guidance during these stages can help buyers understand their responsibilities and avoid unnecessary confusion.
Emaar Property Mortgage: What This Means for Dubai Homebuyers
Emaar is one of Dubai’s prominent property developers, with residential communities and developments across different segments of the market.
The partnership with Huspy adds a financing support option to the customer journey.
For homebuyers, access to more than 20 banks can offer several practical advantages.
- More financing choices: Buyers can explore different bank products through a single process.
- Convenience: They do not need to manage every initial comparison independently.
- Personalised assistance: Dedicated mortgage consultants help buyers understand available options.
- Application support: Guidance is available for pre approval, documentation and bank coordination.
- Support beyond purchase: The service also covers handovers and refinancing.
However, buyers should remember that access to multiple mortgage options does not guarantee the lowest interest rate or automatic loan approval.
The final offer depends on the bank, the buyer’s financial profile and the property being financed.
How KEYSTONE GLOBAL REAL ESTATE Helps Indian Buyers Make Smarter Property Decisions
At KEYSTONE GLOBAL REAL ESTATE, we believe that buying property in Dubai should involve more than selecting an attractive apartment or villa.
For Indian investors and homebuyers, understanding the financial side of a property purchase is equally important.
Our real estate advisory approach focuses on helping clients understand property opportunities, investment objectives and purchasing considerations before making a decision.
1. Property Selection Based on Financial Goals
Every buyer has different objectives.
Some Indian investors prioritise rental income, while others focus on capital appreciation, family accommodation or long term ownership.
Our team helps clients explore suitable property options based on their requirements and investment preferences.
2. Understanding Mortgage and Financing Considerations
Before committing to a property, buyers should understand their potential financing requirements.
KEYSTONE GLOBAL REAL ESTATE helps clients identify important questions to discuss with mortgage specialists, including:
- What is the estimated monthly repayment?
- How much down payment is required?
- Which mortgage structure is suitable?
- What additional purchasing expenses should be considered?
- How does the financing option affect the investment budget?
For personalised mortgage rates and loan approvals, buyers should obtain written offers directly from participating banks or authorised mortgage advisers.
3. Guidance for Indian Investors
Investing in another country requires an understanding of the local property market and purchasing process.
Our team helps Indian clients explore Dubai’s residential property market, understand available communities and evaluate opportunities based on their individual objectives.
From property discovery to transaction guidance, KEYSTONE GLOBAL REAL ESTATE aims to make the buying journey more informed and transparent.
Buying Property in Dubai: Is 2026 a Good Time to Explore Mortgage Options?
Mortgage accessibility is an important consideration for buyers entering Dubai’s property market.
The Emaar and Huspy collaboration introduces a more convenient way for Emaar customers to explore financing options from multiple UAE banks.
For Indian buyers considering a property purchase, this is an opportunity to understand financing choices before making a financial commitment.
However, the right time to purchase depends on individual circumstances.
Buyers should evaluate:
- Their current income and financial stability.
- Available down payment and additional savings.
- Expected mortgage repayments.
- Property location and long term demand.
- Potential rental income.
- Future resale considerations.
- Total ownership and maintenance expenses.
A well planned purchase should balance affordability, investment objectives and long term financial commitments.
Dubai Mortgage Comparison: The Smart Way Forward for Indian Homebuyers
Access to mortgage options from more than 20 UAE banks represents a useful development for Emaar customers.
The partnership with Huspy aims to simplify financing comparisons and provide assistance throughout the mortgage journey, from pre approval to disbursal.
For Indian investors and homebuyers, understanding the available financing options can make property decisions more structured and informed.
At KEYSTONE GLOBAL REAL ESTATE, we encourage buyers to look beyond the advertised property price. Understanding financing, ownership costs, location and long term investment objectives is essential before making a purchase.
Planning to buy property in Dubai? Connect with KEYSTONE GLOBAL REAL ESTATE to explore suitable property opportunities and make a more informed investment decision.
Frequently Asked Questions
1. What is the Dubai Mortgage Comparison initiative by Emaar?
Emaar has partnered with Huspy to provide its customers access to mortgage advisory services and financing options from more than 20 UAE banks through a single process.
2. How many banks are included in the Emaar and Huspy partnership?
The collaboration provides access to mortgage products and financing options from more than 20 banks across the UAE.
3. Can Indian nationals buy property in Dubai through a mortgage?
Yes. Eligible Indian expatriates and non resident Indian buyers may apply for UAE property financing, subject to individual bank requirements, eligibility and approval.
4. Are there any advisory fees under the Emaar and Huspy arrangement?
The announced collaboration states that Huspy will provide its mortgage advisory service to Emaar customers without Huspy advisory fees. Buyers should still confirm any applicable bank and third party charges.
5. What documents are required for a Dubai home loan?
Common documents include a passport, Emirates ID and residence visa where applicable, salary certificate, bank statements, income documents and property details. Requirements vary between lenders.
6. What is the difference between fixed and variable mortgage rates in Dubai?
A fixed rate remains unchanged for an agreed initial period. A variable rate can change according to its applicable benchmark and bank margin. Buyers should review the terms after any fixed period.
7. Can buyers compare mortgage rates from multiple UAE banks?
Yes. Through the Emaar and Huspy collaboration, eligible Emaar customers can compare mortgage products, interest rates and financing terms from more than 20 UAE banks.
8. Does mortgage pre approval guarantee final loan approval?
No. Pre approval is an initial assessment. Final approval depends on the bank’s financial checks, property valuation, documentation and lending conditions.
9. Can an existing homeowner use the service for refinancing?
Yes. The announced service also covers refinancing, allowing eligible customers to explore available financing options for an existing property.
10. How can KEYSTONE GLOBAL REAL ESTATE help Indian property buyers?
KEYSTONE GLOBAL REAL ESTATE assists Indian buyers in exploring Dubai property opportunities, understanding investment considerations and evaluating suitable properties based on their financial goals. For mortgage approvals and personalised financing offers, buyers should consult authorised mortgage advisers and banks.
Join The Discussion